
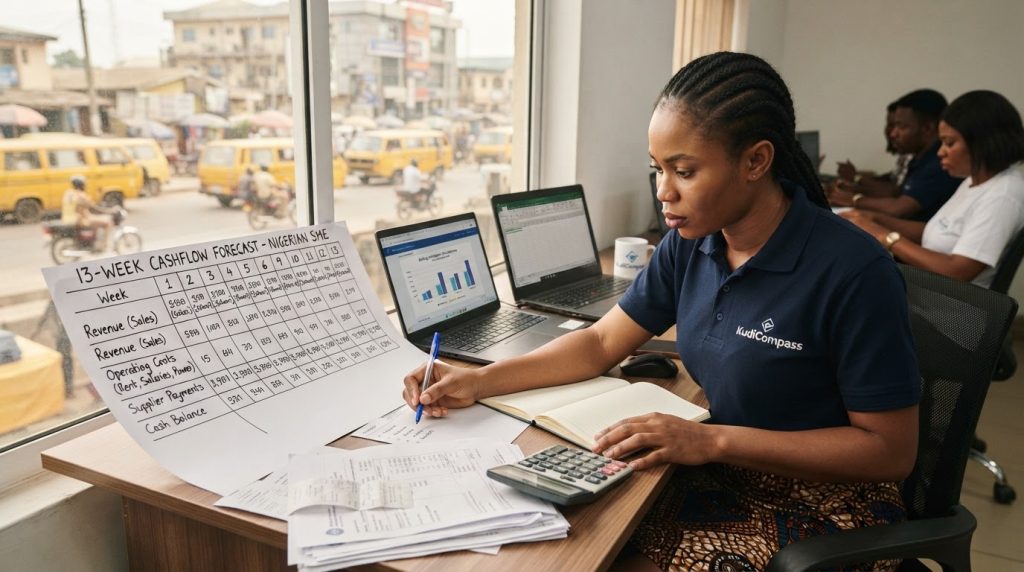
Quick Summary
This guide explains the key costs, trade-offs, and practical steps Nigerian readers should know.
How to Build a 13-Week Cashflow Forecast for a Nigerian Small Business
Your step-by-step guide to predicting cash shortfalls before they happen – with free templates, Naira examples, and Nigeria-specific adjustments
1. Introduction
Every Nigerian small business owner knows the feeling: your profit-and-loss statement says you made ₦500,000 last month, but your bank account is empty. You can’t pay salaries. You can’t restock. You’re profitable on paper but broke in reality.
That gap between profit and cash is what kills SMEs in Nigeria. According to the Zaccheus blog, many Nigerian businesses face irregular payments, forex rate swings, fluctuating input costs, and client payment delays – all of which drain cash unpredictably. A 13-week rolling cashflow forecast catches those shortfalls before your account hits zero.
In this guide, you’ll learn:
- What a 13-week rolling cashflow forecast is and why it matters specifically for Nigerian SMEs
- The exact data, documents, and free tools you need to start
- A step-by-step method to build your forecast, with Naira examples
- Common mistakes that sabotage cashflow forecasting in Nigeria
- A FAQ section answering the questions every SME owner asks
By the end, you’ll have a working forecast and know exactly how to update it every week. Let’s begin.
2. Why a 13-Week Cashflow Forecast Matters for Nigerian Small Businesses
The local reality
Nigerian SMEs operate in a uniquely challenging cash environment. Payments from clients often arrive weeks late – or not at all. The naira’s value can shift dramatically within days. Input costs (especially for imported raw materials) change without warning. And banks charge fees that quietly eat into your balance.
A 13-week rolling forecast – projecting cash inflows and outflows weekly over one quarter – gives you early warning. As the Zaccheus blog explains, “weekly forecasting catches shortfalls before cash runs dry.” It’s not a luxury; it’s a survival tool.
CBN policy impact on borrowing costs
Borrowing money in Nigeria is expensive. At its 306th meeting in July 2026, the CBN’s Monetary Policy Committee retained the Monetary Policy Rate (MPR) at 26.5% and the Cash Reserve Requirement (CRR) for Deposit Money Banks at 45.00% (CBN MPC decisions). That means any loan you take will carry high interest. A cashflow forecast helps you avoid unnecessary borrowing by showing you exactly when you’ll have a surplus or deficit – so you can plan ahead rather than panic-borrow at punitive rates.
Credibility with lenders and investors
When you approach a bank, an investor, or a grant provider in Nigeria, they want to see that you understand your cash position. A robust 13-week forecast demonstrates financial discipline. As the Zaccheus blog notes, it “builds credibility with lenders, investors, and grant providers in Nigeria, and helps monitor debt covenants.”
Real-life example
Consider a Lagos-based retailer who imports beauty products. In early 2026, she built a 13-week forecast and spotted a ₦200,000 shortfall in week 8 – exactly when her supplier’s payment was due. Because she saw it coming, she called the supplier two weeks early and negotiated a 30-day extension. She avoided a cash crisis, a late-payment penalty, and a potential supply cut. That’s the power of forecasting.
3. What You Need Before You Start: Data, Documents, and Tools
Required data
You don’t need perfect records, but the more data you have, the more accurate your forecast will be. Gather:
- Last 3 months of bank statements – from all business accounts (e.g., Kuda Business, Flutterwave, GTBank, Access Bank)
- Sales records – daily or weekly sales figures, including credit sales and expected payment dates
- Expense receipts – rent receipts, supplier invoices, utility bills, POS machine rental fees, bank charges
- Loan repayment schedules – principal and interest due dates
- Known upcoming payments – tax deadlines (VAT, withholding tax, CIT), CAC annual returns, business permit renewals, insurance premiums
Documents you may need later
These aren’t strictly required for the forecast itself, but they’re essential if you plan to apply for a loan based on your forecast:
- BVN (Bank Verification Number) – free at any bank. You can generate it at any commercial bank branch.
- NIN (National Identification Number) – free if you enrol at a NIMC centre; ₦500 for a printed slip if you’ve already enrolled.
- CAC registration – costs between ₦10,000 and ₦50,000 depending on business structure (business name, limited liability company, etc.).
Free templates and tools
You don’t need expensive software. Here are free resources built for Nigerian SMEs:
| Tool | Type | Cost | Key Features |
|---|---|---|---|
| Zaccheus 13-week rolling cash flow template | Excel/Google Sheets | Free download | Weekly columns, opening/closing balance, FX line, receivables buffer |
| Credit Direct 30-day cash flow planner | Free | 5-step CASH FLOW CONTROL SYSTEM, one-page dashboard | |
| Naijapreneur SME Cashflow & Runway Tracker | Online tool | Free | Calculates runway, flags red alert if <3 months |
| Excel/Google Sheets (blank) | Spreadsheet | Free | Fully customizable – best for beginners who want to learn |
Timeline: Gather your data in 1–2 days. Set up your template in 1 hour. The first forecast might take 2–3 hours; weekly updates take 30 minutes.
4. Step-by-Step Guide to Building Your 13-Week Rolling Cashflow Forecast
Step 1: Set up your template
Open a new spreadsheet. Create 13 columns – one for each week – plus a header row. Your rows should be:
| Row | Description |
|---|---|
| Opening Balance | Cash in bank at start of week |
| Cash Inflows | All money coming in |
| Cash Outflows | All money going out |
| Net Cash Flow | Inflows minus outflows |
| Closing Balance | Opening Balance + Net Cash Flow |
Add a row for “Minimum Cash Buffer” (see Step 7). You can also add sub-rows under inflows and outflows for categories (e.g., sales, loan receipts, rent, salaries, raw materials, POS fees).
The Zaccheus blog provides a ready-made template with these exact components.
Step 2: Enter opening balance
Your opening balance for Week 1 is the total cash you have in all business bank accounts right now. If you have ₦850,000 in GTBank and ₦150,000 in Kuda Business, your opening balance is ₦1,000,000.
Be honest – don’t include money you expect to receive but haven’t yet received.
Step 3: Forecast cash inflows
List every expected receipt for each week. Be realistic, not optimistic. Common inflows for Nigerian SMEs:
- Cash sales – daily POS and cash sales
- Credit sales collections – payments from customers who bought on credit (use your accounts receivable ageing report)
- Loan disbursements – if you’ve secured a loan and know the disbursement date
- Investment injections – capital from partners or investors
- Government grants – if you’ve applied and have a confirmed disbursement date
Nigeria-specific tip: If you sell to government or large corporates, expect payment delays of 30–90 days. Build a buffer: assume only 70% of expected credit sales will arrive on time.
The Zaccheus blog recommends using “realistic (not optimistic) assumptions” – it’s better to be surprised by surplus than caught by shortfall.
Step 4: Forecast cash outflows
Categorise your outflows. This is where most Nigerian SMEs get it wrong – they forget the hidden costs. Break outflows into:
Fixed costs (same amount every week/month):
- Rent (e.g., ₦150,000/month for a shop in Ikeja)
- Salaries (e.g., ₦400,000/month for 3 staff)
- Internet (₦15,000/month)
- Generator diesel (₦30,000/week during dry season, ₦50,000/week during rainy season)
Variable costs (change with activity):
- Raw materials or stock purchases
- Marketing spend (social media ads, flyers)
- Transport and logistics
- Fuel for delivery vehicles
Hidden costs (often overlooked):
- POS transaction fees (typically 0.5%–1.5% per transaction)
- Bank maintenance charges (₦50–₦100 per month per account)
- FX losses on imported goods (if you buy dollars at parallel market rates)
- VAT and withholding tax payments (due monthly or quarterly)
- CAC annual returns (₦5,000–₦10,000 depending on company type)
- Insurance premiums (if you have business insurance)
One-time expenses:
- Equipment purchase (e.g., POS machine ₦30,000)
- Business permit renewal (₦10,000–₦50,000 depending on local government)
- Office renovation
The Zaccheus blog emphasises including “POS fees, bank charges, FX losses, tax delays” as specific line items.
Step 5: Add Nigerian-specific adjustments
This is what separates a generic forecast from one that works in Nigeria.
Exchange-rate line: If you import raw materials or finished goods, add a separate row for “USD purchases”. Use the parallel market rate if that’s what you actually pay. For example, if you need $5,000 at ₦1,600/$, budget ₦8,000,000.
Receivables delay buffer: Assume 10% of your accounts receivable will arrive 2 weeks late. If you expect ₦500,000 from a client in Week 3, put ₦450,000 in Week 3 and ₦50,000 in Week 5. The Zaccheus blog recommends this buffer.
Seasonal ramp-ups and dips: December sales might spike 40% above normal; January sales might drop 30%. Adjust your inflows accordingly. If you run a school supply business, August–September is peak; June–July is slow.
Inflation adjustment: Nigerian inflation is high. Add 2–5% per month to variable costs. If raw materials cost ₦200,000 this month, budget ₦204,000–₦210,000 next month. The Zaccheus blog suggests this adjustment.
Periodic local taxes/levies: Many local governments charge annual business permits, development levies, or market fees. Add these in the month they’re due.
Step 6: Calculate net cash flow and closing balance
For each week:
Net Cash Flow = Total Cash Inflows – Total Cash Outflows
Closing Balance = Opening Balance + Net Cash Flow
The closing balance of Week 1 becomes the opening balance of Week 2.
Example (simplified):
| Week | Opening | Inflows | Outflows | Net Cash Flow | Closing |
|---|---|---|---|---|---|
| 1 | ₦1,000,000 | ₦300,000 | ₦250,000 | ₦50,000 | ₦1,050,000 |
| 2 | ₦1,050,000 | ₦200,000 | ₦400,000 | -₦200,000 | ₦850,000 |
| 3 | ₦850,000 | ₦500,000 | ₦300,000 | ₦200,000 | ₦1,050,000 |
In Week 2, you see a negative net cash flow. That’s a warning sign – you need to either boost inflows or cut outflows before that week arrives.
Step 7: Maintain a minimum cash buffer
Never let your closing balance hit zero. The Zaccheus blog recommends keeping 3–4 weeks of expenses or 10–20% of forecasted outflows as a safety net.
Add a row called “Minimum Cash Buffer” and set it to, say, ₦500,000. If your closing balance falls below ₦500,000 in any week, that’s a red flag. You need to act – cut costs, chase receivables, or arrange a credit line before the crisis hits.
Step 8: Run scenario planning
Don’t rely on a single forecast. Create three versions:
- Best case: Sales are 20% higher, all clients pay on time, no unexpected expenses.
- Base case: Your most realistic assumptions.
- Worst case: Sales drop 30%, two major clients delay payment by 4 weeks, fuel prices spike.
The Zaccheus blog recommends running scenario planning to prepare for uncertainty.
Step 9: Update weekly
A rolling forecast means you drop the past week and add a new future week. Every Monday:
- Replace the actual figures for last week (what really happened) with your forecasted figures.
- Compare forecast vs actual – note any variance.
- Add a new Week 13 at the end.
- Adjust your assumptions for the remaining weeks based on what you learned.
The Zaccheus blog says best practices include “update weekly, track variance (forecast vs actual), and align assumptions across sales, procurement, and operations teams.”
5. Common Mistakes Nigerian Small Business Owners Make in Cash Flow Forecasting
Mistake 1: Confusing profit with cash flow
You can be profitable and still go bankrupt. Profit is an accounting concept; cash is what you have in the bank. A customer who buys on credit creates a sale (profit) but no cash until they pay. If you spend based on profit, you’ll run out of cash.
Mistake 2: Ignoring hidden costs
POS fees, bank charges, FX losses, and tax delays silently drain cash. The Zaccheus blog lists these as common oversights. Include every single fee, no matter how small.
Mistake 3: Failing to adjust for inflation and market shifts
If you update your forecast only once a year, it becomes useless. Nigerian prices change monthly. The Zaccheus blog advises updating assumptions quarterly – but in practice, monthly is better.
Mistake 4: Not separating business and personal expenses
Many SME owners use the same account for business and personal spending. This makes cashflow forecasting impossible. Open a dedicated business account – options include Kuda Business (free), Flutterwave (free), or traditional banks like GTBank or Access Bank (₦1,000–₦5,000 monthly maintenance).
Mistake 5: Overestimating revenue
Optimism is natural, but it kills forecasts. Use conservative estimates. If you’re unsure, use the worst-case scenario as your base case. Surplus is a pleasant surprise; shortfall is a crisis.
Mistake 6: Not running scenario plans
A single forecast is fragile. Without best-case and worst-case versions, you’re unprepared for shocks. The Zaccheus blog stresses scenario planning as a best practice.
6. FAQ: People Also Ask About Cash Flow Forecasting in Nigeria
Q: What is a 13-week rolling cash flow forecast?
A: It’s a financial projection that tracks your expected cash inflows and outflows week by week for the next 13 weeks (one fiscal quarter). It’s “rolling” because each week you remove the past week and add a new future week, keeping the forecast horizon constant. The Zaccheus blog defines it as a model that “projects cash inflows and outflows weekly over 13 weeks and is ‘rolling’ because each week you drop the past week and add a new future week.”
Q: How do I forecast cash flow for a small business in Nigeria?
A: Follow the 9 steps in this guide: set up your template, enter opening balance, forecast inflows and outflows, add Nigeria-specific adjustments (FX, receivables buffer, inflation, seasonality), calculate net cash flow and closing balance, maintain a minimum cash buffer, run scenario plans, and update weekly. Use free templates from Zaccheus or Credit Direct.
Q: What is the minimum cash buffer for a Nigerian SME?
A: The Zaccheus blog recommends 3–4 weeks of expenses or 10–20% of forecasted outflows. For example, if your monthly expenses are ₦500,000, keep at least ₦375,000–₦500,000 as a buffer.
Q: How often should I update my cash flow forecast?
A: Weekly. Every Monday, replace last week’s forecast with actual figures, add a new week, and adjust assumptions. The Zaccheus blog lists weekly updates as a best practice.
Q: What tools can I use for cash flow forecasting in Nigeria?
A: Free options include the Zaccheus 13-week rolling template (Excel/Google Sheets), the Credit Direct 30-day planner (PDF), and the Naijapreneur SME Cashflow & Runway Tracker (online tool). Excel/Google Sheets are best for beginners.
Q: How does the CBN’s monetary policy affect my cash flow forecast?
A: With MPR at 26.5% and CRR at 45% (as of July 2026, per CBN MPC decisions), borrowing is expensive. Your forecast should include loan interest costs and avoid relying on debt. High CRR also means banks have less money to lend, so loan approvals may be slower.
Q: Should I include VAT and withholding tax in my forecast?
A: Yes. VAT (7.5%) and withholding tax (5%–10% depending on transaction type) are due monthly or quarterly. Include them as separate outflow line items in the month they’re payable. The Zaccheus blog lists tax delays as a hidden cost to include.
Q: What if my forecast shows a negative closing balance?
A: Act immediately. Options: cut discretionary spending, negotiate extended payment terms with suppliers, offer discounts for early payment from customers, or arrange an overdraft or short-term loan. The forecast gives you time to act – don’t wait until the week arrives.
7. What to Do Next
You now have everything you need to build your first 13-week rolling cashflow forecast. Here’s your action plan:
- Gather your data – bank statements, sales records, expense receipts. Spend 1–2 days on this.
- Download a free template – choose the Zaccheus template or the Credit Direct planner.
- Set up your forecast – follow Steps 1–8 in this guide. Allocate 2–3 hours.
- Review your first forecast – look for weeks where closing balance drops below your minimum buffer. Identify actions to take.
- Start weekly updates – every Monday, update actuals, add a new week, and adjust assumptions. This takes 30 minutes.
- Use the Naijapreneur tracker – as a quick check, input your monthly figures into the Naijapreneur SME Cashflow & Runway Tracker to see your runway. If it’s under 3 months, you’re in the red zone.
- Share with your team – if you have staff, involve them. Align sales, procurement, and operations on the assumptions.
Remember: A cashflow forecast is not a one-time exercise. It’s a living document that grows more accurate the more you use it. Start today, and you’ll never be caught off guard by a cash crisis again.
Disclaimer: This article provides educational guidance only. Always consult a qualified accountant or financial advisor for your specific business situation. All rates, fees, and regulations mentioned are as of September 2026 and may change. Verify with official sources before making financial decisions.