
Quick Summary
This guide explains the key costs, trade-offs, and practical steps Nigerian readers should know.
DMO’s NTB Rejection: What 15.90% Means for Your Savings and Investments
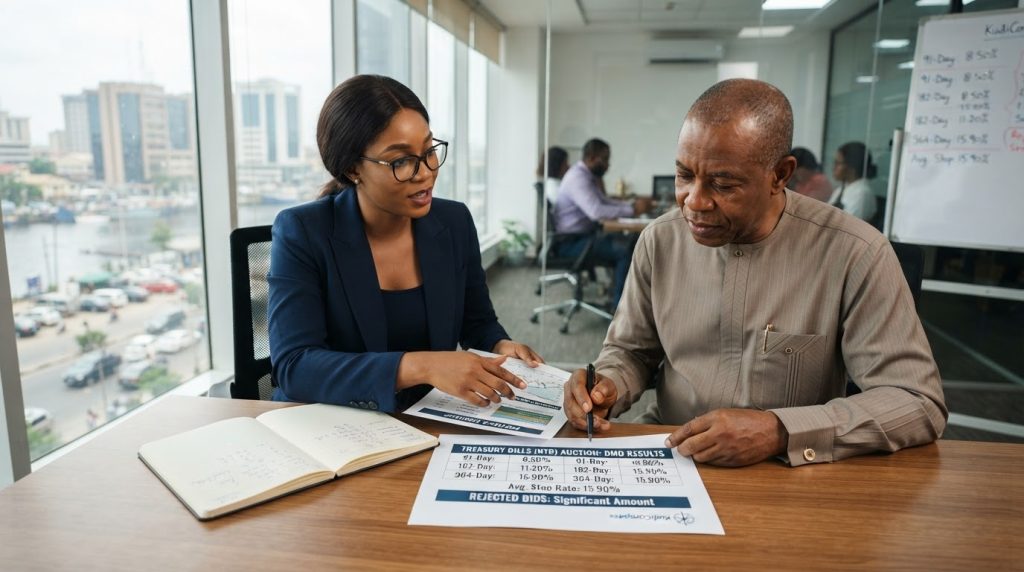
The numbers are stark. At the 14/10/2026 Nigerian Treasury Bills (NTB) auction, conducted by the Central Bank of Nigeria on behalf of the Debt Management Office (DMO), the government turned away roughly three out of every four naira that investors tried to lend to it. Of the N1.032 trillion subscribed across the 91-day, 182-day and 364-day tenors, only N269.06 billion was accepted — an acceptance rate of just 26.07% (CBN Government Securities Summary).
For everyday Nigerians, Treasury Bills are the bedrock of risk-free investing — short-term government IOUs that pay you interest for lending to the federal government. Their rates ripple through everything else: the interest your bank pays on savings, the yield on your money market fund, the returns on your pension contributions, and even the cost of borrowing.
That’s why this auction matters. The one-year stop rate rose to 15.90% — a 5-basis-point increase from 15.85% at the 07/10/2026 auction, and the first increase since August 2026, interrupting the downward trend that followed the CBN’s aggressive 350-basis-point cut to the Monetary Policy Rate (MPR) to 23% on 22/09/2026 (Nairametrics).
This article breaks down what actually happened, what it means for your savings, loans, and investment returns, and how to position yourself in the weeks ahead.
Quick Answer: What You Need to Know Right Now
The direct answer: The DMO rejected approximately 74% of the N1.032 trillion subscribed at the 14/10/2026 auction, accepting only N269.06 billion. The one-year Treasury Bill rate now stands at 15.90% (CBN Government Securities Summary).
What this means for you:
- If you’re a new investor: You can currently lock in 15.90% on one-year T-bills. That’s still attractive by historical standards, but noticeably lower than the 17.59% available in August 2026.
- If you’re a renewing investor: Your rollover will now earn roughly 170 basis points less than two months ago. On a N10 million investment, annual interest drops from approximately N1.76 million at 17.59% to about N1.59 million at 15.90%.
- If you’re a bank saver: Deposit rates at commercial banks typically track T-bill yields. As the government’s cost of borrowing falls, expect banks to gradually trim what they offer on savings accounts and fixed deposits.
- If you hold money market funds: Funds with large T-bill allocations will see their yields compress as they reinvest maturing bills at lower rates.
Key numbers at a glance:
| Metric | Value |
|---|---|
| Total offered across tenors | N450 billion |
| Total subscribed | N1.032 trillion |
| Total allotted | N269.06 billion |
| Acceptance rate | ~26% |
| One-year stop rate | 15.90% |
| Previous one-year stop rate (07/10/2026) | 15.85% |
| One-year bid range | 15.00% – 18.18% |
| One-year subscription | N982.21 billion |
| One-year allotment | N220 billion |
Bottom line: The DMO is signalling it won’t pay whatever the market demands. By rejecting high-priced bids, it is deliberately capping the cost of government borrowing — a classic strategy in a falling-rate environment.
Detailed Analysis: What Happened at the October 14 Auction
The Auction Numbers
The CBN advertised N450 billion across the three standard tenors — N50 billion on the 91-day bill, N50 billion on the 182-day bill, and N350 billion on the one-year (364-day) bill (CBN Government Securities Summary).
Investors responded with overwhelming demand. Total subscriptions reached N1.032 trillion — more than double the advertised offer. But the DMO allotted only N269.06 billion, approximately 40% below the N450 billion it had offered. The rejection was most dramatic on the one-year tenor, which attracted N982.21 billion in bids against a N350 billion offer, with just N220 billion accepted. The Punch captured the scale of the rejection with its headline: “DMO snubs N763bn bids as T-bill rate climbs.”
The Rate Movement
The one-year stop rate rose 5 basis points to 15.90%, from 15.85% at the 07/10/2026 auction — the first increase since August 2026 (Nairametrics).
Context matters. In August 2026, the one-year rate stood at 17.59%. After the CBN’s Monetary Policy Committee slashed the MPR by 350 basis points to 23% on 22/09/2026, rates fell sharply in successive auctions. The 14/10/2026 auction marks the first time the market pushed back — even slightly — against that decline.
Investors bidding for the one-year bill quoted rates between 15.00% and 18.18%. The DMO set the marginal (stop) rate at 15.90%, meaning bids at or below that level were accepted; investors demanding 18% or anything above the stop rate were rejected (CBN Government Securities Summary).
Why Did the DMO Reject So Many Bids?
The federal government wants cheaper debt. With the CBN cutting the MPR aggressively as part of its monetary easing cycle, the DMO is using its rejection power to anchor yields lower. If it accepted all N1.032 trillion on offer, it would be locked into borrowing costs near the top of the bid range for the next year. Instead, it accepted only what it needed at rates it considered acceptable.
This is a classic move in a falling-rate environment. The DMO is effectively telling investors: “If you want government paper, you take our price.” And because T-bills remain the safest naira-denominated asset in the country, many investors eventually comply.
The 5-basis-point concession on the stop rate shows the DMO had to bend slightly to attract sufficient bids. But it held firm against the double-digit demands above 18%.
What This Means for the Broader Market
For banks: Nigerian commercial banks hold substantial T-bill portfolios as part of their liquidity management. As yields fall, their interest income from these securities declines. Over time, their cost of funds also falls, which could translate into cheaper lending rates for borrowers. But the adjustment is rarely symmetrical — banks typically reduce deposit rates faster than they cut loan rates. If you have a variable-rate loan, don’t expect an immediate reduction; if you have savings, expect your interest rate to drift lower within weeks.
For fixed-income funds: Money market funds and bond funds hold large T-bill allocations. As they reinvest maturing bills at lower rates, their published yields will compress. This affects funds offered by banks like Stanbic IBTC, Fidelity, and UBA, as well as fintech savings platforms such as PiggyVest, Cowrywise and Risevest that route customer funds into money market instruments. Your principal is not at risk, but your monthly returns will shrink over the coming months.
For the naira: Foreign portfolio investors are drawn to Nigerian T-bills primarily because of high yields. As rates fall, the attractiveness of naira assets diminishes, which could reduce foreign inflows and add pressure on the exchange rate. However, the CBN’s broader policy stance suggests it is prioritising domestic economic growth over defending the currency at elevated yield levels.
For pension contributors: RSA funds are heavily invested in federal government securities under PenCom regulations. As T-bill yields moderate, pension fund returns will follow. This does not put your retirement savings at risk — it simply means the growth rate may slow compared to the heights of early 2026.
Comparison Table: NTB Rates Across Recent Auctions
| Auction Date | One-Year Stop Rate | Change (bps) | Amount Allotted | Subscription | Acceptance Rate |
|---|---|---|---|---|---|
| August 2026 | 17.59% | — | Not verified | Not verified | Not verified |
| 07/10/2026 | 15.85% | Down from August | Not verified | Not verified | Not verified |
| 14/10/2026 | 15.90% | +5 bps | N269.06bn | N1.032trn | ~26% |
Sources: CBN Government Securities Summary; Nairametrics
Note: Allotment and subscription figures for the August and 07/10/2026 auctions were not available in the verified data at the time of writing. The August 2026 rate of 17.59% is confirmed by Nairametrics’ report.
Alternative Investment Comparison
| Investment Option | Approximate Yield | Risk Level | Liquidity |
|---|---|---|---|
| 1-Year NTB (current) | 15.90% | Risk-free (government-backed) | High (sellable in secondary market) |
| 91-Day NTB | Below 1-year rate | Risk-free | Very high |
| 182-Day NTB | Mid-range between 91-day and 1-year | Risk-free | High |
| Bank Fixed Deposit | Varies by bank; typically below T-bill rates | Low (NDIC insured up to N500,000) | Medium (lock-in period) |
| Money Market Fund | Tracks T-bill rates | Low | Very high |
Exact stop rates for the 91-day and 182-day tenors at the 14/10/2026 auction are available on the CBN Government Securities DrillDown page. Current verified data on specific bank fixed deposit offers was unavailable at the time of writing — check directly with your bank for today’s rates.
What This Means for Your Wallet
If You Have Money in a Savings Account
The era of meaningful savings account interest is being squeezed further. Nigerian banks have historically paid between 1% and 4% on regular savings accounts — well below T-bill yields. As T-bill rates fall, banks face less pressure to compete for deposits. Your savings are protected by the NDIC up to N500,000 per depositor per bank, but protection from bank failure doesn’t protect you from losing purchasing power. If inflation runs close to or above your savings rate, your money is quietly shrinking in real terms.
If You Invest in Fixed Deposits
Fixed deposit rates are closely tied to T-bill yields. Banks need to borrow from depositors at rates below what they could earn by lending to the government — otherwise, there’s no incentive to take deposits at all. With the one-year T-bill at 15.90%, expect fixed deposit renewal offers to come in below your previous rate. If your fixed deposit matures in the next 30 days, compare your bank’s renewal offer against the current T-bill rate before rolling over.
If You’re a Pension Contributor
Your RSA contributions are invested primarily in FGN securities. The yield on your pension fund will moderate as T-bill rates decline. For young contributors, this is a minor consideration over a 20-30 year horizon. For those nearing retirement, it’s worth reviewing your fund’s recent performance and understanding how much of its return came from the elevated rates of 2025 and early 2026.
If You’re Considering T-Bills Today
At 15.90%, one-year T-bills still offer a solid nominal return — historically high compared to the single-digit yields of the pre-2023 era. But locking in for a full year means accepting that you’ll earn 15.90% even if rates move higher. If you need flexibility, the 91-day tenor allows you to reinvest more frequently and catch rising rates. If you want certainty, the one-year tenor locks in today’s yield. There is no universally “correct” choice — it depends on your view of where rates are headed and when you need your money.
If You’re a Borrower
Falling T-bill rates eventually feed into cheaper borrowing costs. Banks price loans off their cost of funds, which is influenced by the yields they earn on government securities. As the CBN’s rate-cutting cycle progresses, expect mortgage rates, SME loans, and personal loan offers to gradually decline. But the transmission takes time — typically several months — and banks are often quicker to cut deposit rates than loan rates.
Frequently Asked Questions
What exactly is a Treasury Bill? A Treasury Bill is a short-term government security issued by the CBN on behalf of the Federal Government. You’re essentially lending money to the government, which repays you at maturity with interest. Because it’s backed by the full faith of the federal government, it’s considered the safest naira-denominated investment available.
How do I buy Treasury Bills in Nigeria? You can buy T-bills through any commercial bank, primary dealer, or licensed investment platform. You’ll need your Bank Verification Number (BVN) and a valid means of identification (NIN, international passport, or driver’s licence) for Know-Your-Customer (KYC) compliance. The minimum investment is typically N10,000 for retail investors through bank channels. You can also buy T-bills on the secondary market through licensed stockbrokers and investment houses.
Why did the DMO reject so many bids? The DMO rejected roughly 74% of bids to keep government borrowing costs down. By accepting only lower-priced bids, it caps how much interest the government will pay on new debt. This is a deliberate strategy, not an accident or an administrative error.
Is 15.90% a good return for T-bills? That depends on inflation. If inflation is running below 15.90%, you’re earning a positive real return. If inflation is above that level, you’re losing purchasing power despite the nominal interest. In the context of recent Nigerian history, 15.90% is significantly lower than August’s 17.59% but far above the single-digit rates seen before 2023.
Will my bank’s savings rate change because of this? Indirectly, yes. Banks adjust deposit rates based on their cost of funds and the yields available on government securities. As T-bill yields fall, banks typically reduce savings account and fixed deposit rates. The adjustment usually happens within weeks to a few months.
Are my money market fund investments safe if rates fall? Yes, your principal is generally safe — money market funds invest in low-risk instruments like T-bills, commercial paper, and bank placements. What changes is the yield: as funds reinvest at lower rates, your monthly returns will decline. You won’t lose your capital, but your income from the fund will shrink.
Do I need to pay tax on Treasury Bill interest?
No — for individual investors, Treasury Bill interest is exempt from Personal Income Tax in Nigeria. Banks and the CBN do not deduct withholding tax on T-bill earnings, which gives T-bills a clear edge over fixed deposits: a bank will typically deduct 10% withholding tax from your fixed deposit interest at source, while your T-bill maturity proceeds arrive without any tax deduction. For companies and other corporate investors, the position under the Companies Income Tax Act has been amended several times in recent Finance Acts, so if you’re investing through a business entity, have your tax adviser confirm the current treatment before you buy.
Can I sell my T-bills before maturity?
Yes. T-bills trade on the secondary market, so you can exit before maturity through your bank or a licensed stockbroker. You’ll receive the prevailing market value of the bill, which depends on how interest rates have moved since your original purchase. If market rates have fallen, your bill is worth more than you paid; if rates have risen, it’s worth slightly less. Because T-bills are highly liquid and government-backed, the bid-ask spread is usually narrow, making them one of the easiest fixed-income investments to convert back to cash.
How do I actually receive the interest?
T-bills are issued at a discount. Instead of receiving regular interest payments, you buy the bill for less than its face value and receive the full face value at maturity. For example, a N100,000 one-year T-bill at a 15.90% stop rate would cost roughly N86,300 today; at maturity, the government repays the full N100,000 — the N13,700 difference is your interest. You never see the interest as a separate payment, which can confuse first-time buyers, but the economics are identical to earning 15.90% on your money.
What to Do Next
- Verify today’s rate before you commit. Auction results change every two weeks. Before buying, check the latest stop rates on the CBN’s Government Securities DrillDown page or ask your relationship manager for the most recent auction outcome rather than relying on the figure in this article.
- Check the auction calendar. The CBN holds NTB auctions roughly every fortnight. If you want to participate in the primary auction, your application must reach your bank before the bidding deadline — usually a day or two before the auction date. Buying on the secondary market through your bank’s trading desk is the alternative if you miss the deadline.
- Review your maturing investments now. If you have a T-bill, fixed deposit, or money market holding that matures within the next month, don’t let it roll over automatically. Ask about the new rate first and compare it against the current auction rate. Automatic rollover at a lower rate is the quietest way to lose yield.
- Match tenor to your cash needs. Use the 91-day bill if you need access within a quarter, the 182-day bill for a half-year horizon, and the 364-day bill to lock in today’s 15.90% for a full year. If you’re unsure, consider splitting your money across two tenors to build a simple ladder.
- Buy through your bank’s app. Most major Nigerian banks now let you apply for T-bills directly on their mobile apps or internet banking platforms. You’ll need your BVN and a valid ID for first-time KYC, and the minimum retail investment is typically N10,000. The app will show you the stop rate, the discount price, and the maturity value before you confirm.
- Keep an eye on the MPC and inflation data. The next Monetary Policy Committee decision and inflation release will influence where stop rates go next. If inflation keeps declining, the CBN’s easing cycle is likely to continue pushing rates down; if inflation surprises on the upside, the rate cut path may pause. Whatever happens, check the verified auction result rather than reacting to headlines.
- Remember the tax advantage. A N5 million one-year T-bill at 15.90% earns N795,000 in interest — tax-free for individuals. The same principal in a 14% fixed deposit earns N700,000 gross, but after 10% withholding tax you’d walk away with about N630,000. On the same money, T-bills put roughly N165,000 more in your pocket, even before considering the risk difference.
The Bottom Line
The Treasury Bill rate in Nigeria has clearly turned a corner: from the 20%+ peaks that defined 2025 and early 2026, the one-year stop rate has fallen to 15.90% at the October 2026 auction — and the DMO’s aggressive bid rejection, turning away roughly 74% of bids at the sale that produced that rate, shows the Federal Government is determined to keep borrowing costs moving lower. For savers, pension contributors, and investors, the message is consistent: the era of 20% risk-free returns is over, and locking in today’s rates while repositioning for a lower-yield environment is the sensible play. Verify every rate on the CBN’s official page, compare it against your bank’s renewal offers, and make your tenor decision based on your own cash-flow calendar — not on forecasts you read online. The market will keep moving, but a disciplined routine of checking the verified auction data before every purchase will always serve you better than any headline.